Divorce involves more than deciding where each spouse will live or how much time children will spend with each parent. One of the most important financial issues is determining how to divide the couple’s assets and debts. Homes, bank accounts, retirement plans, vehicles, credit cards, business interests, personal property, and other financial obligations may all need to be identified and allocated.
The process can become complicated when spouses disagree about ownership, the value of property, or who should be responsible for certain debts. Understanding how asset and debt division generally works can help you prepare for the financial side of divorce and make informed decisions.
What Does It Mean to Separate Assets and Debts?
Separating assets and debts means determining which property belongs to each spouse and deciding how marital financial obligations should be handled after the divorce.
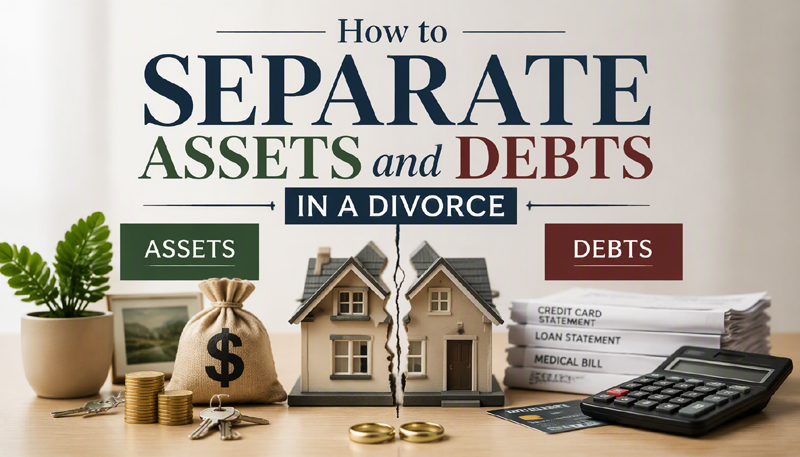
Assets may include:
- Real estate and family homes
- Bank and savings accounts
- Investment accounts
- Retirement accounts and pensions
- Vehicles
- Businesses and professional practices
- Stocks and other investments
- Valuable personal property
- Jewelry and collectibles
- Life insurance cash value
- Intellectual property
- Certain employee benefits
Debts may include:
- Mortgages
- Credit card balances
- Auto loans
- Personal loans
- Student loans
- Medical bills
- Business debts
- Tax obligations
- Other marital financial liabilities
The exact rules depend on the state where the divorce is filed. Some states follow community-property principles, while others use equitable-distribution rules.
Step 1: Understand Marital and Separate Property
One of the first steps is determining whether property is marital or separate.
Marital property generally refers to assets acquired by either spouse during the marriage, regardless of whose name appears on the account or title. Depending on state law, this can include income earned during the marriage, property purchased with marital funds, and increases in value of certain assets.
Separate property generally refers to property owned by one spouse before marriage or property received individually through certain gifts or inheritances. However, separate property can become partially or entirely subject to division if marital funds or both spouses’ efforts were used to improve or increase its value.
For example, suppose one spouse owned a house before the marriage. If the mortgage was paid using marital income during the marriage or both spouses contributed substantially to renovations, the other spouse may have a claim depending on applicable state law.
Because the classification of property can be complicated, keeping documentation from before and during the marriage can be extremely important.
Step 2: Make a Complete List of Assets
Before dividing anything, create a detailed inventory of everything the spouses own.
Start with major assets such as the family home, vehicles, retirement accounts, investment accounts, and businesses. Then include smaller but valuable items such as electronics, jewelry, furniture, collectibles, and valuable personal belongings.
Financial records may help identify assets that are easy to overlook.
Useful documents can include:
- Bank statements
- Investment statements
- Retirement account statements
- Property deeds
- Mortgage documents
- Vehicle titles
- Tax returns
- Business records
- Insurance policies
- Loan statements
- Credit card statements
- Employment benefit information
Do not assume that an asset is separate simply because it is held in one spouse’s name. Ownership and marital classification can depend on when and how the asset was acquired.
Step 3: Determine the Value of the Assets
Knowing what you own is only part of the process. You also need to determine what those assets are worth.
Some assets have an obvious value. A bank account, for example, may be valued based on its current balance. Other assets can be much more difficult to value.
Real estate may require a professional appraisal or a comparative market analysis. Businesses may require a business valuation. Vehicles can often be valued using established market data, while jewelry, artwork, collectibles, and other valuable property may require specialized appraisals.
Retirement accounts also deserve careful attention because their stated balances may not represent the amount that would actually be available after taxes, penalties, or other considerations.
Accurate valuations can help spouses negotiate a fair division of property.
Step 4: Identify and Classify Debts
Debts should be reviewed just as carefully as assets.
Make a complete list of all outstanding obligations and identify when each debt was incurred and how it was used.
For example, a credit card used to pay household expenses during the marriage may be treated differently from a debt incurred by one spouse for an entirely personal purpose, depending on state law and the circumstances.
Common debts to examine include mortgages, credit cards, car loans, personal loans, medical expenses, student loans, and tax liabilities.
Do not overlook debts simply because they are not in your name. Depending on state law, you may have financial responsibility for certain marital obligations even if your name does not appear on the account.
Step 5: Understand Your State’s Property-Division Rules
The rules for dividing property vary significantly among states.
In community-property states, marital property is generally divided equally or according to community-property principles. However, the specific rules and exceptions vary by state.
In equitable-distribution states, marital property is generally divided in a manner the court considers fair. Fair does not necessarily mean an exact 50/50 split.
Courts may consider factors such as each spouse’s financial circumstances, contributions to the marriage, earning capacity, duration of the marriage, and other legally relevant factors.
Because state law can significantly affect the outcome, it is important to understand the rules that apply to your particular divorce.
Step 6: Consider the Family Home Carefully
The family home is often one of the largest assets involved in a divorce.
Spouses may decide to:
- Sell the home and divide the proceeds.
- Have one spouse buy out the other spouse’s interest.
- Allow one spouse to remain in the home temporarily.
- Continue co-owning the property for a specific period.
If one spouse keeps the home, the parties need to consider more than its market value. They should also examine the mortgage balance, property taxes, insurance, maintenance costs, and other expenses.
For example, a home worth $500,000 with a $350,000 mortgage does not represent $500,000 of available equity. The mortgage and other relevant costs must be considered when determining the net value.
Step 7: Deal With Retirement Accounts
Retirement accounts can represent a substantial portion of a couple’s marital wealth.
These may include 401(k) plans, pensions, IRAs, and other retirement benefits. Depending on the account and applicable law, dividing retirement assets may require special procedures and documents.
Some workplace retirement plans may require a Qualified Domestic Relations Order (QDRO) or another appropriate court order before funds can be transferred to a former spouse without triggering certain consequences.
Do not simply withdraw money from a retirement account and divide it yourself without understanding the tax and legal consequences.
A financial professional or qualified family-law attorney can help determine the appropriate process.
Step 8: Address Joint Credit Cards and Loans
One of the biggest mistakes people make during divorce is assuming that a divorce decree automatically removes their responsibility for joint debts.
It generally does not.
If both spouses signed a loan or credit-card agreement, the creditor may continue to hold both borrowers responsible even if the divorce judgment says one spouse must pay the debt.
For example, if a divorce agreement requires one spouse to pay a joint credit card but that spouse stops making payments, the creditor may still pursue the other spouse if both remain legally liable under the original credit agreement.
Where possible, spouses may consider refinancing, transferring balances, closing joint accounts, or otherwise restructuring debts so that responsibility is clearly separated.
Step 9: Watch for Hidden or Undisclosed Assets
Most divorces depend on complete financial disclosure. Unfortunately, disputes can arise when one spouse believes the other has failed to disclose assets.
Potential warning signs may include unexplained withdrawals, unusual transfers, undisclosed bank accounts, sudden changes in financial activity, or missing financial records.
If you believe assets have been hidden, do not attempt to access accounts illegally or take confidential information without authorization. Instead, discuss your concerns with your attorney and use appropriate legal discovery procedures.
Financial records, tax returns, account statements, business documents, and other evidence may help identify missing assets.
Step 10: Create a Property-Division Agreement
If spouses can reach an agreement, they may be able to create a written settlement addressing their property and debts.
A comprehensive agreement may specify:
- Who receives each major asset
- Who keeps the family home
- How bank and investment accounts are divided
- How retirement accounts are handled
- Who receives specific personal property
- Which spouse is responsible for each debt
- How vehicles and loans are handled
- What happens to jointly owned businesses
- How future financial obligations will be addressed
The agreement should be clear and specific. Vague language can create disputes later.
What Happens If You Cannot Agree?
Not every couple can reach an agreement.
When spouses disagree, the court may ultimately determine how marital assets and debts are divided. The process may involve financial disclosures, discovery, appraisals, expert valuations, negotiations, mediation, hearings, and potentially a trial.
Going to court can be expensive and time-consuming, so many couples attempt negotiation or mediation before asking a judge to decide every financial issue.
However, settlement is not always appropriate in every situation. If there are significant financial disputes, suspected hidden assets, business interests, or substantial debts, professional legal guidance can be particularly valuable.
Common Mistakes to Avoid
Several mistakes can make the financial side of divorce more difficult.
Failing to Gather Financial Records
Without accurate records, it can be difficult to determine what exists, when it was acquired, and how much it is worth.
Assuming Everything Is Divided 50/50
Property-division rules vary by state. An equal division is not necessarily the legal standard in every jurisdiction.
Ignoring Debt
A spouse may focus heavily on receiving assets while overlooking the debts attached to those assets.
Forgetting Taxes
Some assets can have significant tax consequences. A retirement account, investment, or property sale may not have the same after-tax value as another asset with the same stated value.
Closing Accounts Without a Plan
Closing or changing financial accounts without understanding the legal consequences can create unnecessary complications.
Relying on Verbal Agreements
Financial agreements should generally be documented properly. A verbal promise that one spouse will “take care of the debt” may not provide sufficient protection.
Final Thoughts
Separating assets and debts is one of the most important financial steps in a divorce. The process usually begins with identifying all property and liabilities, determining whether they are marital or separate, establishing accurate values, and applying the property-division rules of the appropriate state.
The goal is not simply to divide everything in half. The objective is to reach a legally appropriate and financially workable division while protecting your interests and planning for life after divorce.
If your divorce involves significant property, retirement accounts, a business, substantial debt, real estate, or disagreements about ownership, consider consulting a qualified family-law attorney and, when appropriate, a financial or tax professional. Professional advice can help you understand your rights, evaluate settlement proposals, and avoid costly mistakes.This article provides general educational information and is not legal advice. Divorce and property-division laws vary by state and individual circumstances. For advice about your specific situation, consult a licensed attorney in your jurisdiction.